Robert Caplin Bloomberg Getty Images
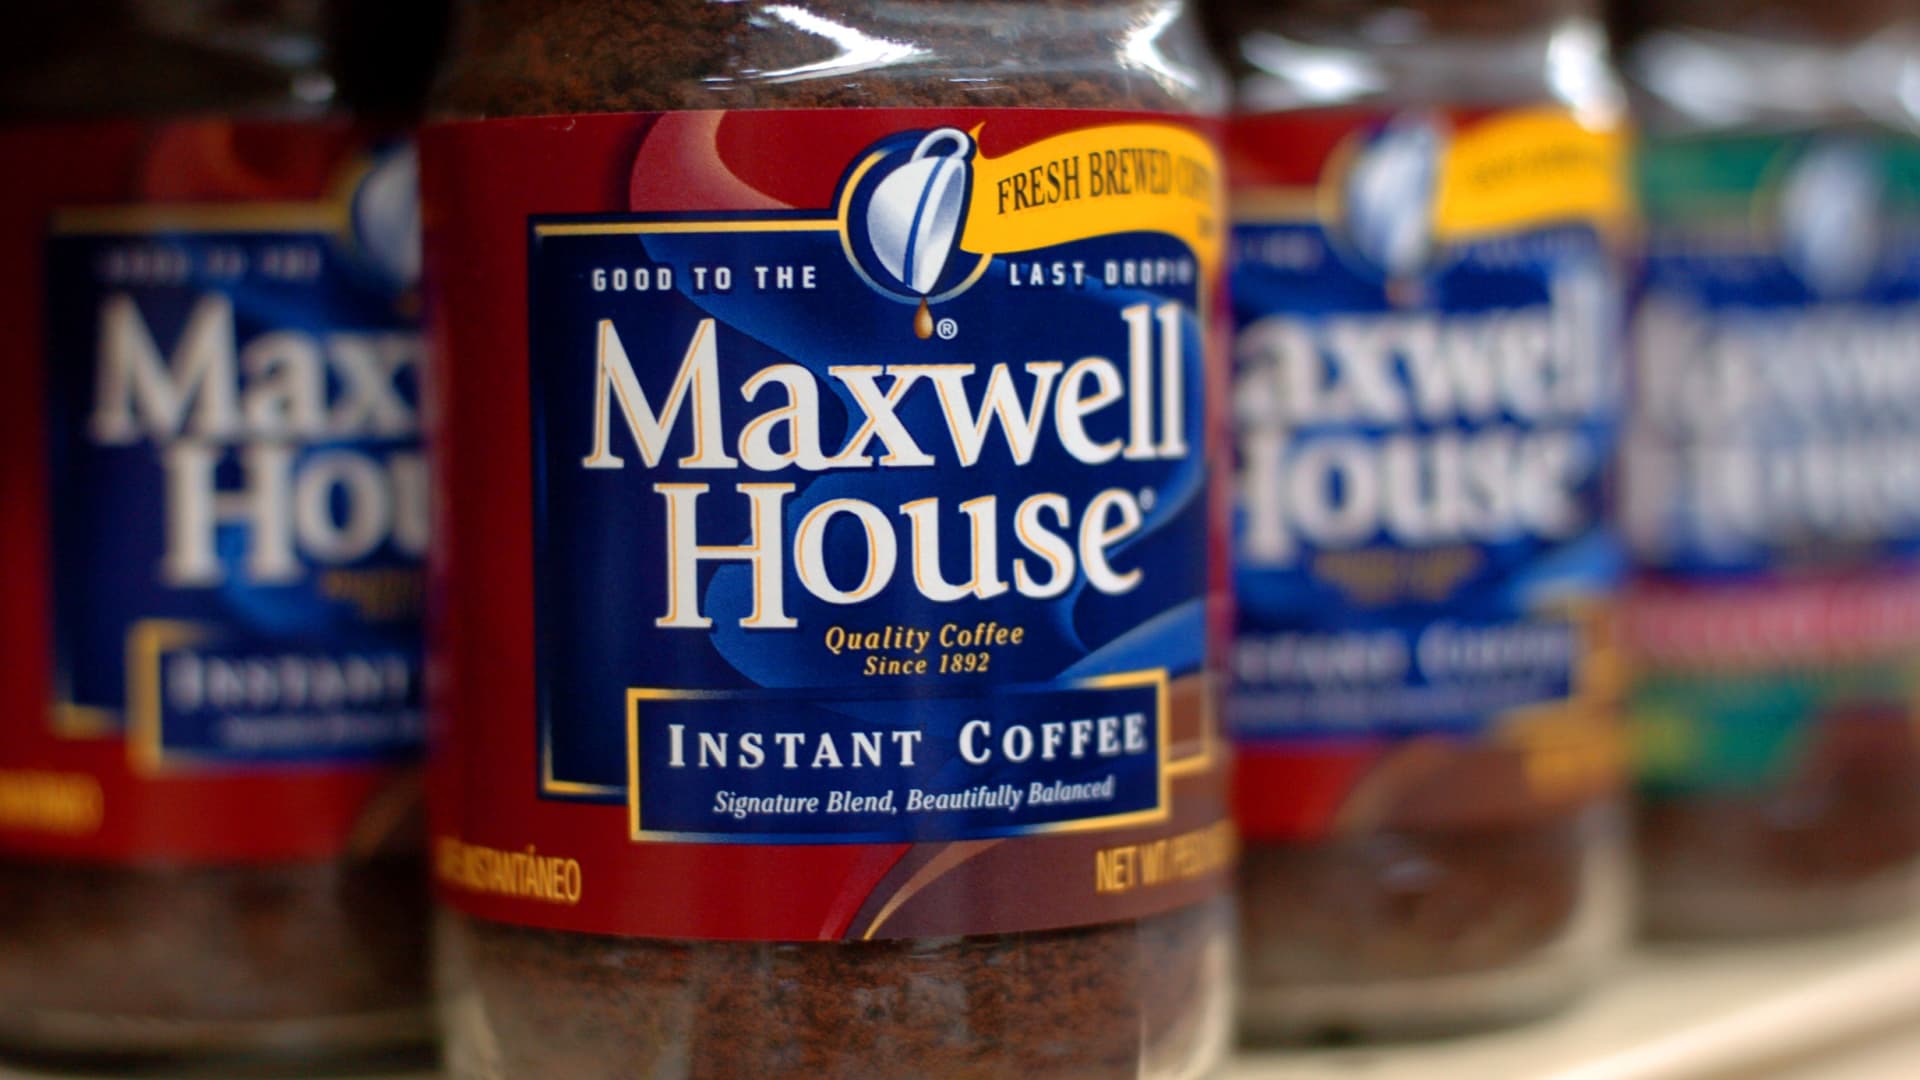
Kraft Heinz announced Wednesday that it will release its coffee unit in North America in a deal that values the business at $650 million on a corporate basis, as it works to refocus on its core brands.
The deal with private equity firm One Rock Capital Partners includes brands such as Maxwell House and Gevalia and is expected to close by mid-2027, the company said in a press release. Kraft Heinz will retain a 30% noncontrolling stake in the business.
Kraft Heinz said it will use $500 million of post-tax cash proceeds from the transaction to pay down debt as it works to prioritize resources where it can accelerate growth.
“This transaction is a meaningful step in unlocking our portfolio and will accelerate the momentum behind our transformation,” Steve Cahillane, CEO of Kraft Heinz, said in the release.
Cahillane joined the company in January and put on hold plans to split the company in two, a move that would have reversed the $46 billion blockbuster merger of a decade ago. He said the problems facing Kraft Heinz are “fixable and controllable.”
The turnaround effort has included a $700 million investment back into the business and a sharp focus on some core brands.
Also on Wednesday, Kraft Heinz reported third-quarter earnings that beat expectations and raised its outlook for 2026. It now expects organic net sales to fall 0.5% to 1.25%, an improvement from its second-quarter report, which projected sales could fall as much as 2%.
“Our 2026 operating plan to pivot our US business and accelerate international growth is in place,” Cahillane said. “Relative to last year, market share, sales, and volume trends are improving in every region. We are increasingly meeting consumers everywhere, and giving them more reasons to choose our brand.”
The company’s shares were up about 5% Wednesday morning.