Kimberly-Clark shareholders need good news. We have been given many gifts this week. On Thursday alone, the makers of Kleenex and Huggies reported better-than-expected preliminary results for the third quarter, and Chinese authorities rejected claims social media had hurt diaper sales in the country. The one-two punch comes just days after European regulators signed off on a planned acquisition of Kenvue, the owner of Band-Aid, Tylenol and other health and wellness brands. Brazilian regulators have begun to follow suit, legal news service MEx reported on Friday. Meanwhile, the turbulence for the AI trade has also boosted defensive parts of the market, including the consumer-staples corner where Kimberly-Clark resides. The positive development has sent the stock up about 8% this week, including a gain of more than 1% on Friday. That puts it at the top of the Club portfolio leaderboard. The stock is on pace for its best weekly performance since October 2022. Kimberly-Clark is also on track for its first weekly gain since mid-August. Shares rose 3.4% last week. This is a much-needed reversal of fortunes for Kimberly-Clark after a 9.75% decline in September. Although we have used the weakness since the beginning of September 2 to increase the position, it is encouraging to see Kimberly-Clark starting to accumulate some wins ahead of the expected Kenvue takeover – the big reason we have shares. The most recent purchase was Tuesday. “It’s a major name … and it’s hated because the last few quarters haven’t been good,” Jim Cramer said Friday on CNBC. “But if they merge with Kenvue … it’s going to dovetail perfectly. This is what we want to be in.” Kimberly-Clark’s strong week as AI trading wobbled reinforced why we bought the stock in the first place: the desire to withdraw exposure to data centers. While Kimberly-Clark checks its own boxes, its pending acquisition of Kenvue adds a fundamental catalyst to bolster its investment case. That didn’t stop the stock from having the first few weeks in our portfolio, but now the tide is turning. An early look at Kimberly-Clark’s third-quarter numbers was a relief. For the three months ended in September, the company reported preliminary revenue of $4.13 billion and earnings per share of $1.70, both beating Wall Street estimates. Kimberly-Clark will publish full results and continue the usual earnings call on November 5. The initial financial disclosure is likely to be connected to the Kenvue deal process. The sneak-peek results were so encouraging because of the update of Kimberly-Clark’s disappointment at the Barclays Global Consumer Staples Conference on September 9. That’s when CFO Nelson Urdaneta warned that two-quarter sales and EPS were tracking below the current Wall Street consensus, sending shares down 4.1% – the second worst day. Executives pointed to several headwinds emerging since Kimberly-Clark’s August earnings report that led to revised expectations: Product launch delayed due to production problems, distributors in its professional business replenishing inventory at a slower pace than they sell, and freight and logistics costs were higher during the third quarter. The company said it was more vulnerable to transportation costs than usual because of the April fire at its California distribution center, which added $30 million to $40 million in additional costs. Just hours before Kimberly-Clark released preliminary results, Chinese authorities confirmed that no formamide had been found in baby diapers, according to the state-owned China Daily, denying allegations circulating on Chinese social media that the popular Huggies diapers contain the toxic chemical. The diaper-quality controversy has weighed on Kimberly-Clark’s second quarter sales in China and contributed to the guidance for the full year, adding to the concerns of investors about the prospects of organic growth. Although Huggies sales may not bounce back immediately, the official disclaimer from the Chinese authorities is an important step on the road to recovery in the country. It also helps clean up the Kimberly-Clark story as the company makes progress in completing the Kenvue acquisition, which Jim sees as a major catalyst for the stock. Kimberly-Clark expects the acquisition, which was announced in late November, to close before the end of the year. After closing, Kimberly-Clark will be the second largest consumer health and wellness company by revenue, behind only Procter & Gamble. On Tuesday, the European Commission approved the acquisition on the condition that Kimberly-Clark divest some of its feminine hygiene brands in the region. This is a critical regulatory milestone needed to help the deal across the finish line. To cap off the week, Brazilian regulators also signed off on the deal, according to MLex. The company did not immediately respond to CNBC’s request for comment on the agreement. At Thursday’s Monthly Meeting, Jim predicted that Brazil’s stamp of approval would be forthcoming. Another hurdle to completing the transaction was cleared Tuesday, when Kimberly-Clark said it received enough support from Kenvue’s bondholders to exchange debt on Kenvue for new bonds issued by the company. Jim believes Kimberly-Clark can unlock value from the maker of Tylenol, which was spun off from healthcare giant and Johnson & Johnson Club name in 2023 and is struggling to find its footing as an independent entity. With Kenvue under its roof, Kimberly-Clark will be able to reduce input costs by negotiating contracts between materials produced together. Mergers of this size also typically see headcount reductions to reduce costs. Strategically, Jim also expects Kimberly-Clark CEO Michael Hsu to strengthen Kenvue’s weak business areas, such as e-commerce. In general, Kenvue is attractive to Kimberly-Clark because it will increase exposure to health and wellness more directly, benefiting from the demographic tailwinds of an aging population. “I still believe Kenvue doesn’t have an e-commerce strategy… That would be great,” Jim said. Jim expects the combined company to win on Wall Street, in part because it offers consumer analysts new ideas to push their investor clients. Currently, only 39% of Wall Street analysts have a buy rating on Kimberly-Clark’s stock, according to FactSet data. “I was ready to hear the mellifluous voice of ‘keep buying Kimberly.’ … At this point, they want something fresh that’s also cheaper,” Jim said Thursday night. “This is just how the Street works. Now go try to make some money from it, not as a trade, though, but as an investment, because I believe this Kimberly-Clark upgrade is coming, and you want to get ahead of them. (Jim Cramer’s Charitable Trust long KMB. Read here for a complete list of shares.) As a subscriber of the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling shares in the portfolio If Jim has talked about the stock on CNBC, he waits 72 hours after issuing a trade. THE ABOVE INVESTMENT CLUB IS SUBJECT TO THE TERMS AND CONDITIONS AND THE DISCLAIMER. No fiduciary obligations or duties are made available in connection with the investment club.
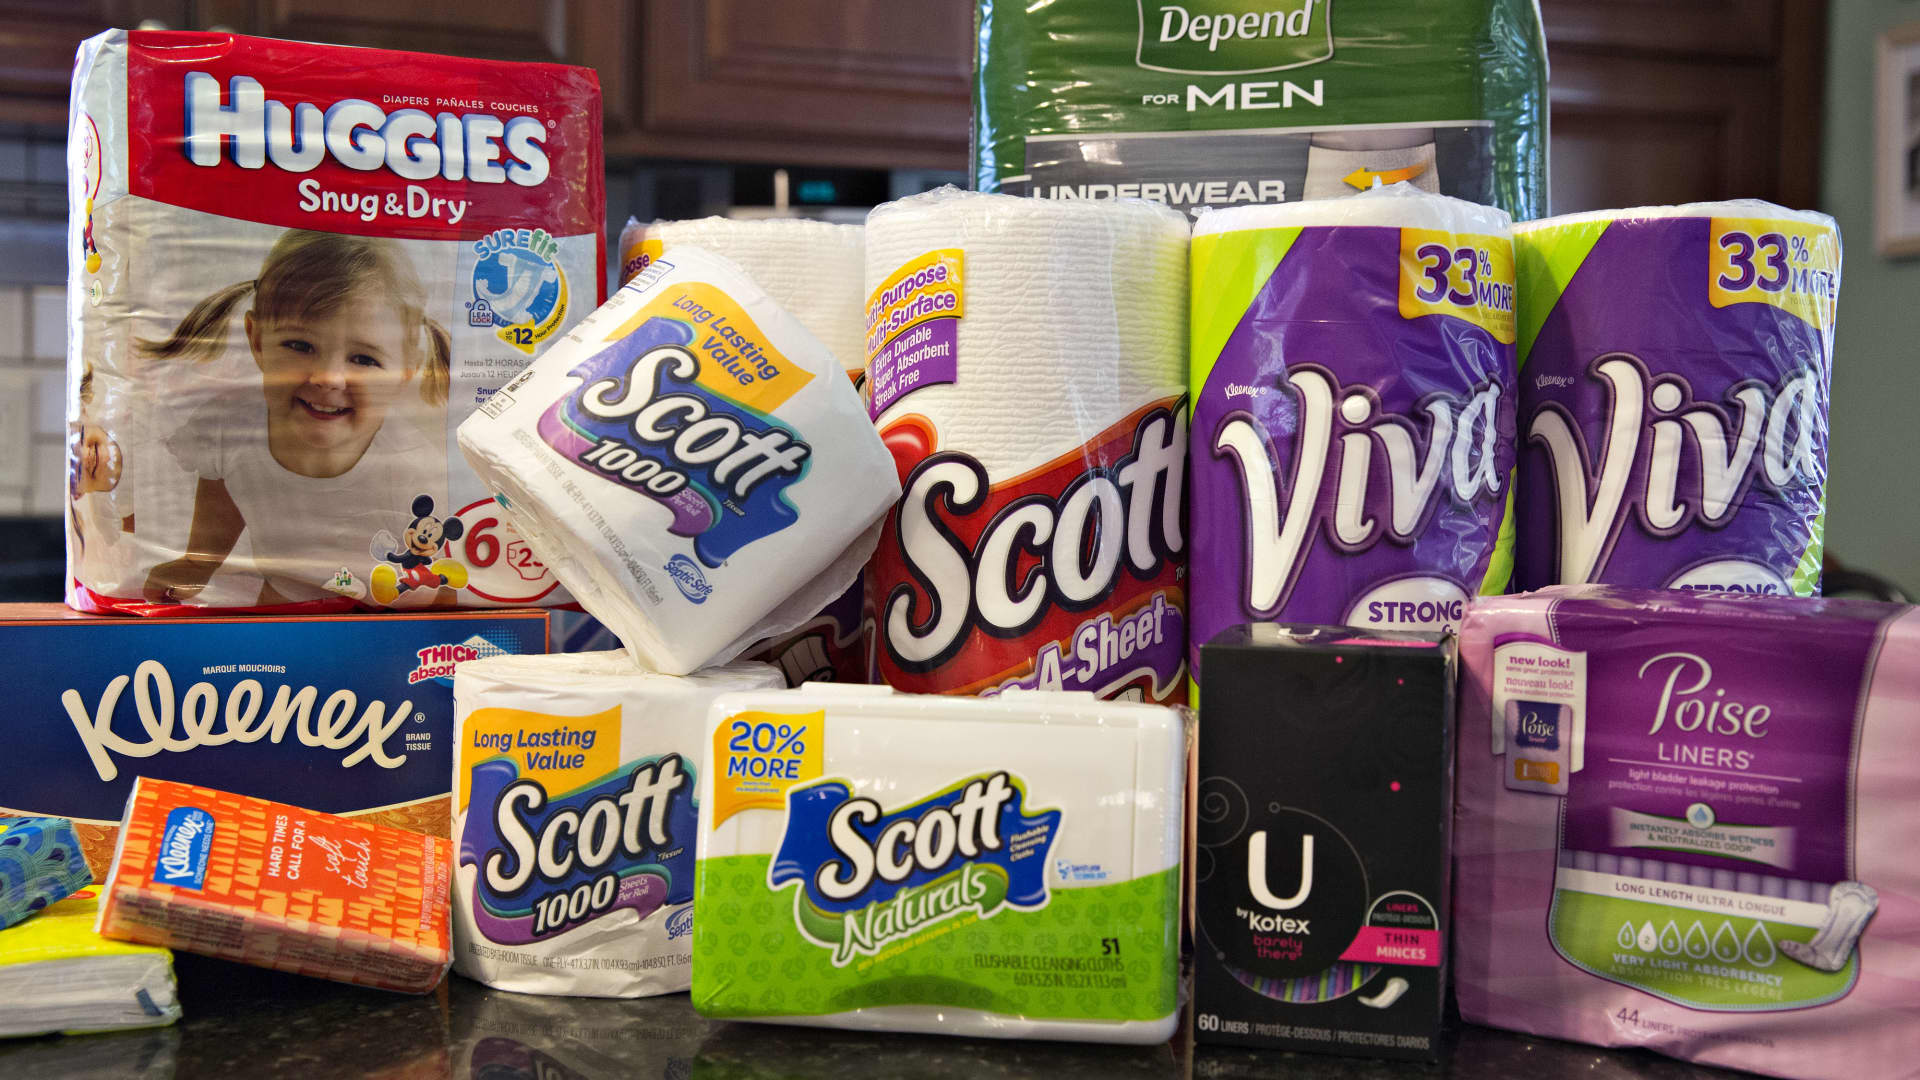
Kimberly-Clark had its best week in four years. Here’s what’s driving the stock higher