Forbes magazine just published an annual list of the 400 richest Americans, who this year have a total of $8 trillion in wealth. That’s a huge amount of money, but we also live in a world where there are no trillions. Here are some thoughts and perspectives.
Social Security benefits promised under current law exceed projected revenue streams by about $29 trillion over the next 75 years, according to actuaries. Medicare benefits promised under the law now exceed projected revenue streams by about $60 trillion over the next 75 years. So, if the U.S. government had an additional $8 trillion to play with, it could address about one-quarter of Social Security’s underfunding or about one-eighth of Medicare’s underfunding—but not both. The first point here is simply that the wealth of the US held by the richest is enormous, it is not an infinite amount; indeed, the promises that have been made by only these two programs are greater.
However, there is no question that US wealth is growing faster than the economy as a whole. This figure shows the wealth-to-GDP ratio in the US since 1960.
From the 1960s to the 1980s, the ratio of US total wealth to GDP was about 4—that is, with some fluctuations, total assets increased in proportion to the size of the economy. But in the 1990s, this changed. There was a stock market wealth explosion in the 1990s and a real estate wealth explosion in the early 2000s, and in 2007 on the eve of the Great Recession, wealth was 4.9 times the size of GDP. After the Great Recession, the wealth-to-GDP ratio fell back to a historical level of around 4. But a few years later, led mainly by rising stock prices (which have risen almost six times since 2010), the wealth-to-GDP took off again, topping out at 5.5 times at the end of 2021 and 2022, and now it seems to sink a new one.
This pattern affects how we think about rising inequality. If the wealth-to-GDP ratio remains the same over the same period, but the top 1% or 0.1% have a larger share, then the wealth at the top will come at the expense of the wealth in the middle and bottom. But with a rising wealth-to-GDP ratio, the amount of absolute wealth in the middle and bottom can stay the same, even as the amount of wealth increases at the top. One could argue that both scenarios are unpleasant, and I wouldn’t argue emphatically, except that both scenarios are unpleasant in different ways and have different implications.
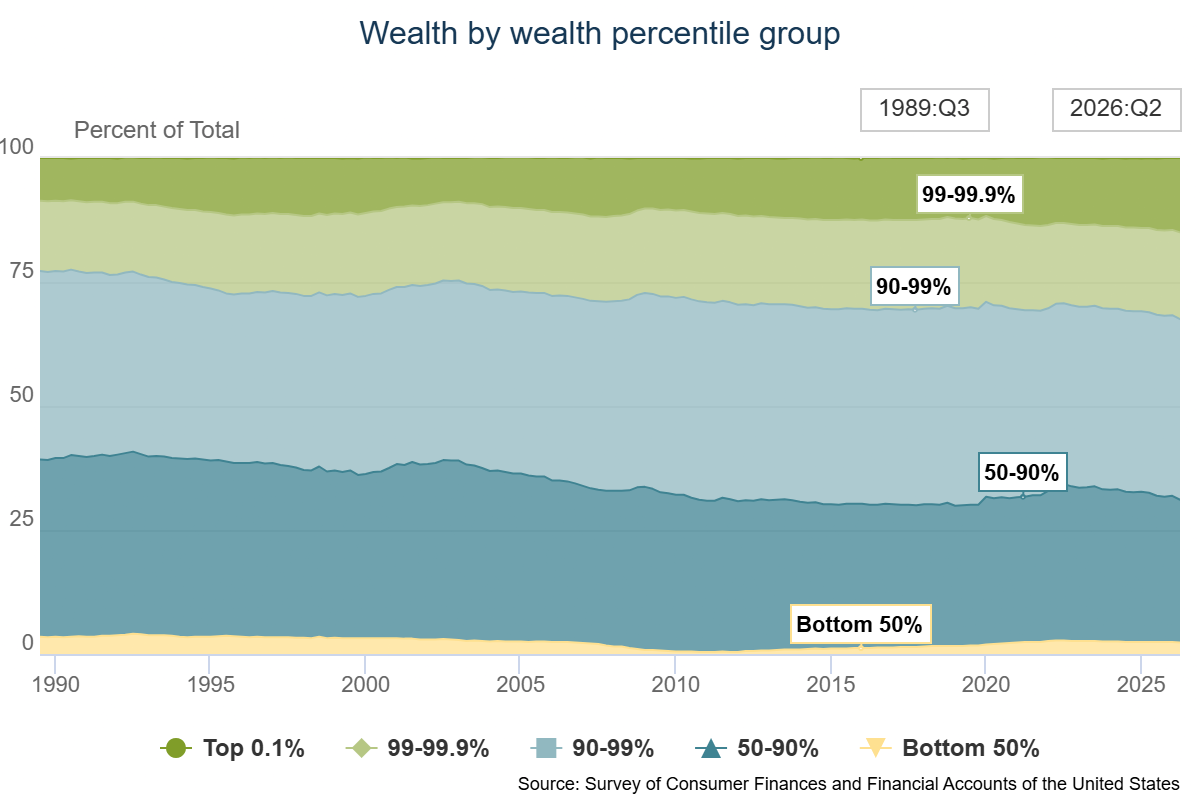
The Federal Reserve now runs a website with detailed wealth data, updated monthly. This figure shows the share of wealth held by different groups. This is household data, so with 134 million or more households in the US (and an average of 2.5 people per household), the top 1 percent consists of 1.34 million households. The top 1% held 8.6% of the total wealth in 1989, and how about 15% of the total wealth. Meanwhile, the bottom 90% of the wealth distribution held 77.2% of the total wealth in 1989, but now hold 68.3% of the total wealth.
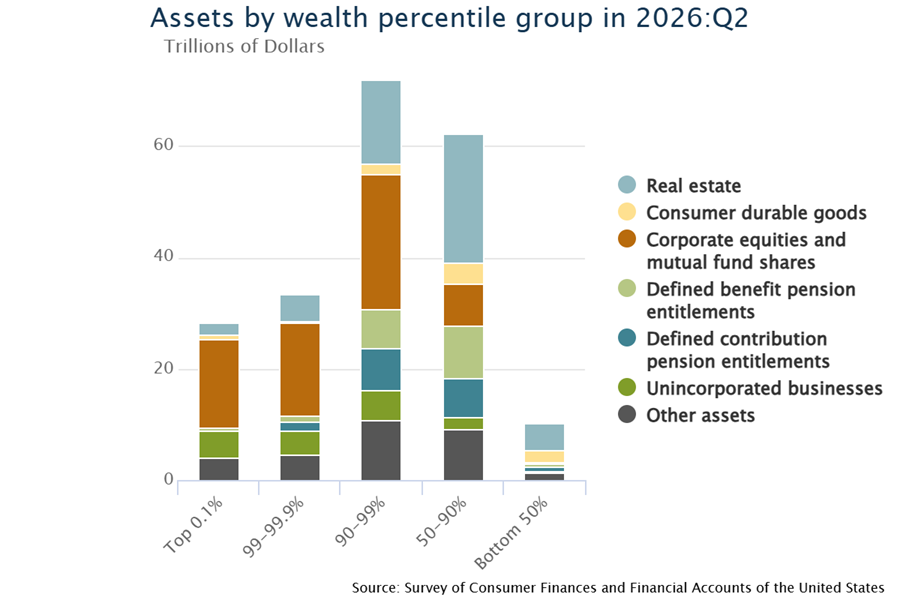
This figure shows the type of assets held by various groups: again, remember that the number of households is represented by the first bar, above 0.1%, only one ninth as large as the second bar, and both are smaller than the bars that follow.
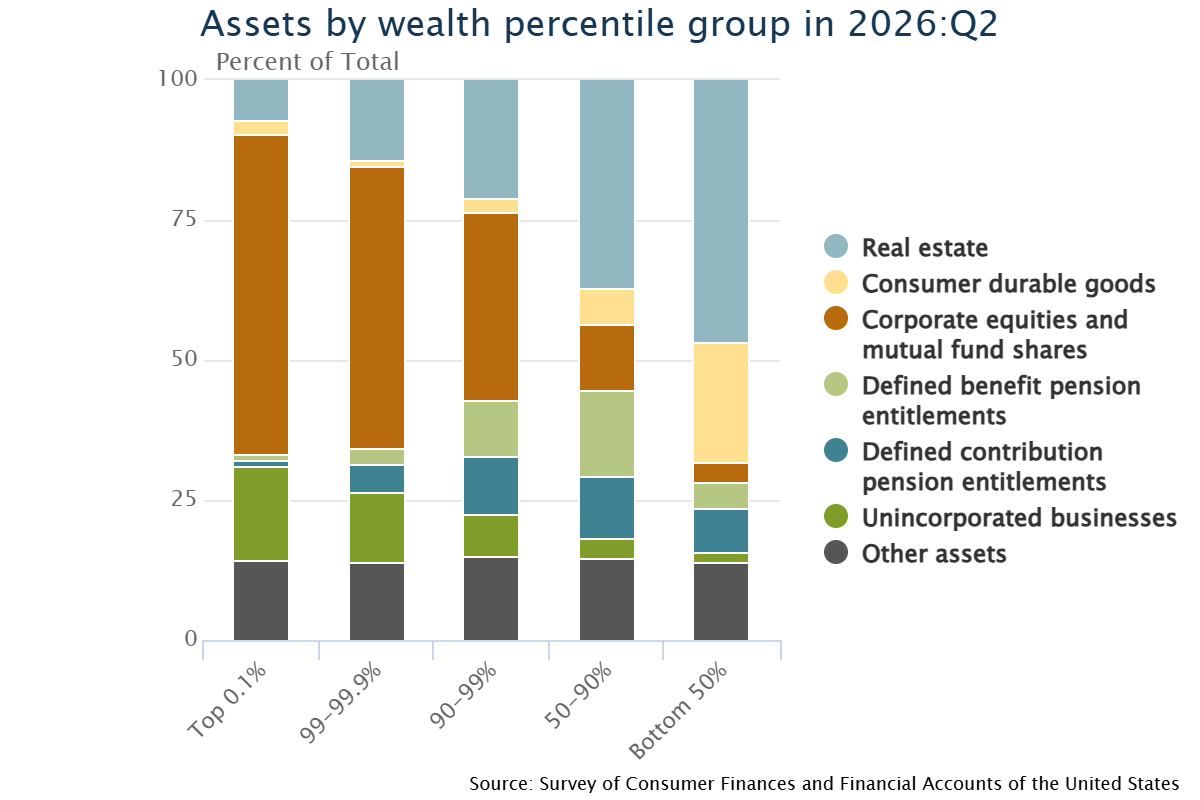
The next figure shows the same data, but instead of presenting it in dollars, it shows the share of assets held by each group. What’s interesting here, I think, is that those at the top of the wealth distribution are more likely to hold assets in the form of stocks and “unincorporated businesses.” hare the assets held by each group. Those further down the distibution have a greater share of wealth in real estate.
There are several proposals for a wealth tax, but in my own mind, it seems important that some European countries that try to tax wealth then withdraw it. One of the common problems is that exclusions and exclusions have been built into the law: for wealth held by family farms, for wealth in other family businesses, for historical properties, for family heirlooms, for works of art, etc. Another problem is how to value wealth that is not bought and sold in the market, and another problem is what happens when wealth is held in other countries. I have discussed here some more practical alternatives to the wealth tax, like focusing on the rules that allow the value of the asset to “go up” at death, so that the heirs do not pay tax on capital gains before (see here and here). Indeed, just rolling back the US estate tax rules to 2004–which was hardly the time of the forfeiture tax–could raise about $100 billion a year.