
PreJust a few years ago, real estate investors were salivating over apartment buildings as rents increased at a historic pace. But as oversupply continues to collide with the latest increases in borrowing costs, multifamily is out of favor, at least for now.
Increasing distress now appears inevitable for apartment owners hoping for interest rates to drop as lenders shift to asset classes that generate better yields, executives said last week in BisnowNational Commercial Real Estate Finance Event.
About $1.8T in debt will be owed to multifamily owners over the next decade, with $757B due between now and 2028, The Wall Street Journal reported.
“I’m not saying it’s going to be as bad as the office,” said Rialto Capital Head of Special Situations Investments Joe Bachkosky. “But it creates a challenge for an asset class that’s probably been one of the stronger asset classes in the last 25, 30 years.”
Higher borrowing costs have challenged owners who take out loans between 2020 and 2022. Interest rates are close to zero at that time, and rents have doubled in the cities of the Sun belt. The dynamics are slowing down – apartment prices fell by almost 5% between August 2025 and August 2026, according to MSCI. Overall CRE prices were flat over the same window.
Without solid returns, multifamily is “difficult,” Clarion Partners Managing Director and Head of US Transactions Gary Rufrano said on stage at the Marriott Marquis Times Square.
“People now have to see some performance spectacles and stop seeing the obstacles on the ground for people to get conviction a lot more in the multi,” he said.

Bisnow/Ciara Long
Gibson, Matthew Gibbons of Dunn & Crutcher, Benjamin Nevid of Meridian Capital Group, Joe Bachkosky of Rialto Capital, Andy Field of Oxford Properties and Jeffrey Steiner of Steiner Capital & Consulting LLC on stage at Bisnow’s National Commercial Real Estate Finance event
Stubborn inflation and soaring government debt have pushed the 10-year Treasury yield – the benchmark for most commercial real estate borrowers – over 5.3%, the highest level since 2022. The increase has occurred as commercial and multifamily mortgage delinquencies have been inching up across most types of lenders, according to the latest Mortgage data from the Mortgage Bank.
The Federal Reserve’s rate hikes confirm that interest rates will not fall again, which changes the tenor of the conversation between lenders and borrowers.
Even for properties that perform well, if they have debt issued before 2023, they may be at risk of foreclosure, Oxford Properties Group Senior Managing Director of Investments Andy Field said.
“These days are good. Maybe there are some basics that will tell you in the market. But when there is maturity, there may be an event,” He said.
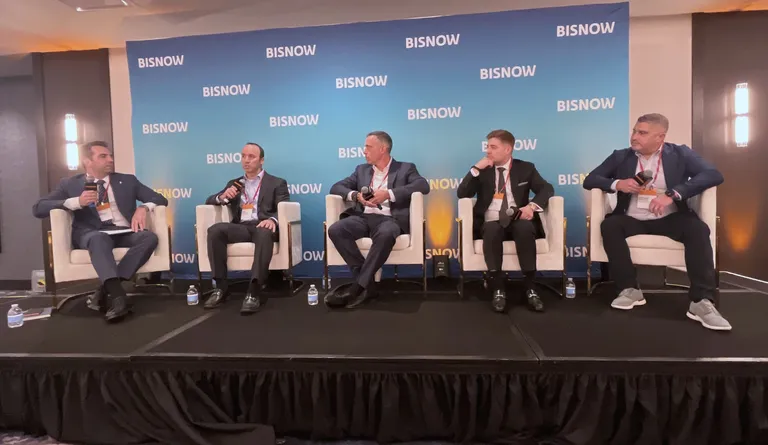
Bisnow/Ciara Long
Ryan Steve Thompson, Clarion Partners Gary Rufrano, Wafra David Hamm, Legal 1031 Exchange Services Paul Faglione and Hunton Andrews Kurth Matthew Scoville
While rents have soared in New York and San Francisco in the past year, the fundamentals of multifamily ownership in other states are “quite painful,” said Wafra Senior Managing Director David Hamm.
Oversupply has led to high demand in some markets, particularly in Sun Belt cities. Meanwhile, operating costs have been rising for years, increasing by nearly 37% between 2019 and 2026, from $6,950 to $9,510 per unit, according to Harvard University’s Joint Center for Housing Studies.
“Rents aren’t growing as much as expenses,” Bachkosky said. “You have to put capital in. Not to increase your rent – you just have to put capital in to keep your rent where it is.”
Rialto has long been one of the most active CMBS loan specialty servicers, tasked with dealing with borrowers who are unable to pay their mortgages at maturity.
A third of the loans recently transferred to Rialto’s servicing platform are multifamily, up from almost none a decade ago, Bachkosky said. Rialto currently has $14B in multifamily loans that need training.
“It’s so funny because three or four years ago, apartments were the golden child,” said Steve Thompson, principal at tax specialist Ryan. “They can do no wrong, and it’s just to see how things change.”
About 8% of multifamily CMBS loans were delinquent in August, up from 6.5% a year ago, according to Trepp. Only offices have higher delinquency rates among major property types.
Because multifamily is the largest asset class and there is still a nationwide housing shortage, investors are still looking to invest in apartments. Bachkosky says things can go wrong in this environment.
“What’s more unusual about this cycle is that multifamily is going to be very difficult,” he said. “There is still a lot of capital that is ready to be invested [multifamily]don’t recognize some of the problems that exist.
Those sentiments were echoed on a separate panel by GoldenTree Asset Management principal and Real Estate Chief Sam Friedland, who questioned the discipline of lenders underwriting apartment loans today.
“A lot of people who make these loans don’t think about the risk they’re registering at the point of leverage they’re providing,” he said.
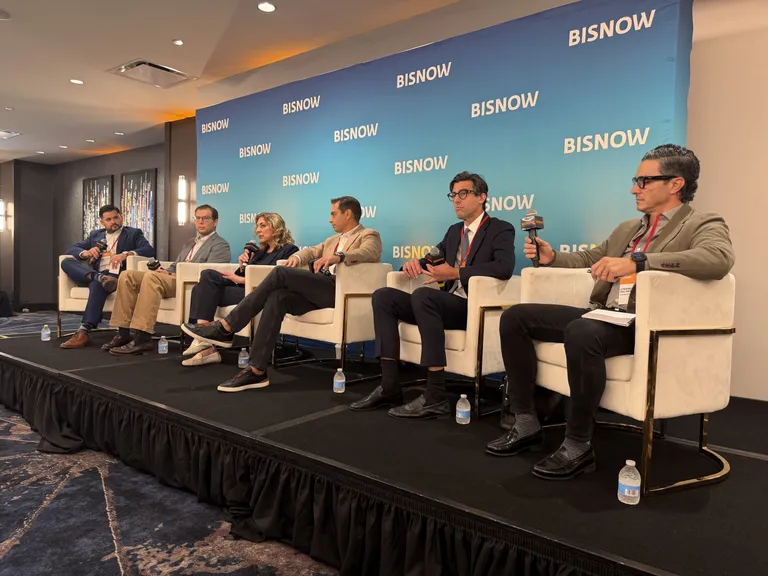
Bisnow/Ethan Rothstein
Kevin Burns of Citrin Cooperman, Robbie Pinkas of PACE Loan Group, Hailey Ghalib of Affinius Capital, Ran Eliasaf of Northwind Group, Sam Friedland of GoldenTree Asset Management and Stephen Palmese of Integritas Capital
Liquidity issues have plagued pockets of the multifamily market, particularly syndicators who pool equity to buy large portfolios with high leverage points. Last month’s interest rate hike could lead to another series of companies, said Northwind Group founder and Managing Partner Ran Eliasaf.
“I think we’re going to see a second wave of these Tides [Equities]” he said, referring to a value-added syndicator that defaults on loans covering a 30,000-unit Sun Belt multifamily portfolio due to interest rate increases in 2023.
“They’re hoping that rates will go in a different direction,” Eliasaf said of many multifamily investors. “They’re not going to be able to support a property where rates are now. It’s going to be a very tough market.”
In the meantime, investors are finding many options that offer better short-term returns.
“You can love it or hate it, but offices are fully priced,” Hamm said, adding that retail has become a favorite asset class of sovereign wealth fund-backed investment firms over the past few years.
Industrial also returned to success stories after a period of overbuilding, Rufrano said. Investors were surprised last year when President Donald Trump announced a tariff policy, but consumers have not pulled back spending.
“People still like to sit on the couch and buy things,” he said. “As long as that happens, the industry will be in demand.”
Despite the current multifamily problem, investors still believe it will become fashionable again. The sector has lower long-term volatility than other asset classes, said Meridian Capital Group Senior Managing Director Benjamin Nevid, because people always need a place to live.
However, squeezed between high borrowing costs, debt coming due and investor misgivings about how multifamily owners present their fundamentals, the sector could be in for a bumpy ride over the next few years.
“We like the long term,” Hamm said. “We don’t like the price right now.”