Positive spread terms in Canada until September. But the term spread signals a recession for 2024 (which some have predicted). What can be taken from this, regarding the possibility of a recession?
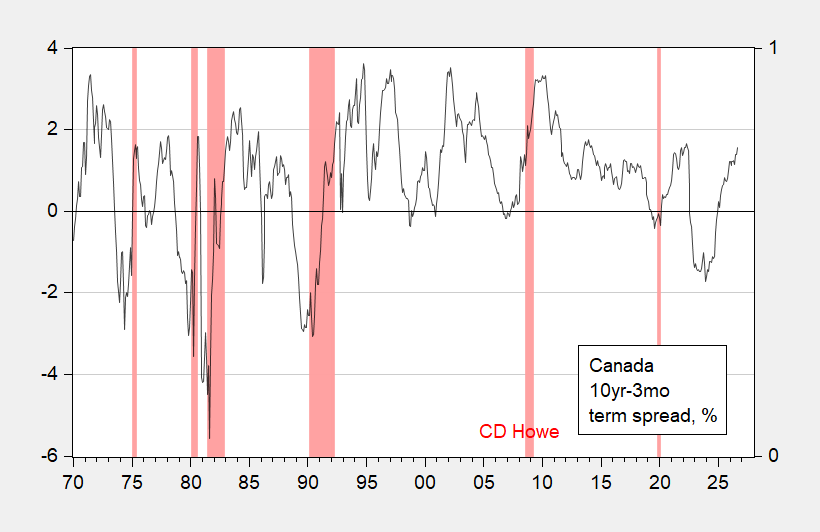
In part, the answer depends on which recession you have identified. That one depends on the interpreter. For Canada, there are at least three: CD Howe, ECRi, and Philip Cross as updated. Here are the 10yr-3mo spreads and their respective recession dates (peak-to-trough).
Figure 1: Canadian 10yr-3mo spread, % (black line), and CD Howe peak recession date (pink shading). Source: OECD, CD Howe.
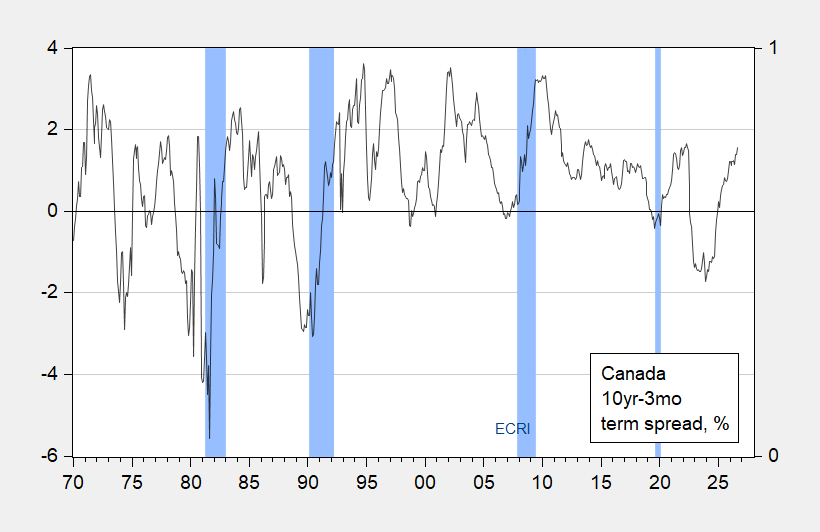
Figure 2: Canadian 10yr-3mo spread, % (black line), and ECRI peak-to-trough recession dates (pink shading). Source: OECD, ECRI.
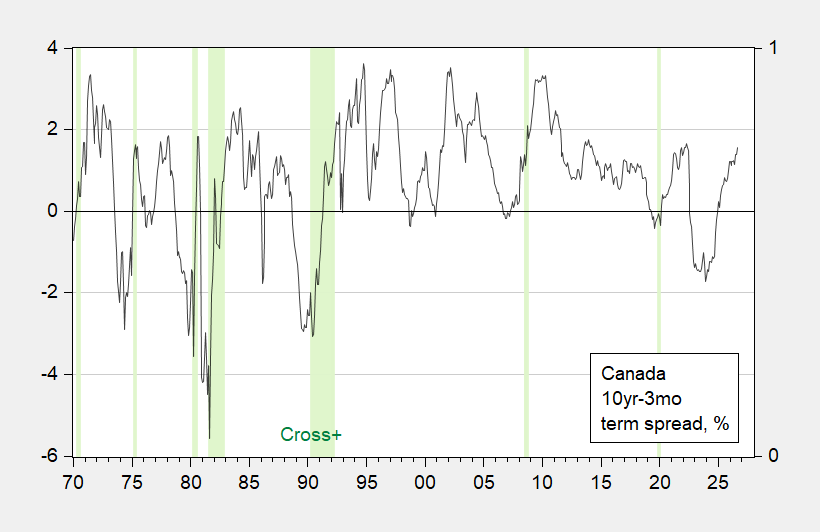
Figure 3: Canadian 10yr-3mo spread, % (black line), and peak-to-trough recession dates (pink shading). The 2020 recession is set to coincide with the ECRI date. Source: OECD, Cross (1996) as updated by Hao and Ng (2011).
As noted in Chinn and Ferrara (2026), the 10yr-3mo term spread model – estimated on pre-pandemic data – will predict the 2024 recession (using a 40% threshold), but will miss the 2008 recession (as well as the 2020 recession). Using the entire sample, a recession would be predicted using the 35% threshold.
Using some of the same specifications reported in Chinn and Ferrara (2026) for the US ( blogpost here ), we find that the regression plus debt service will also predict a recession, using a threshold of 40%. The term premium augmented specification will not have (although this is estimated in the sample is shorter).
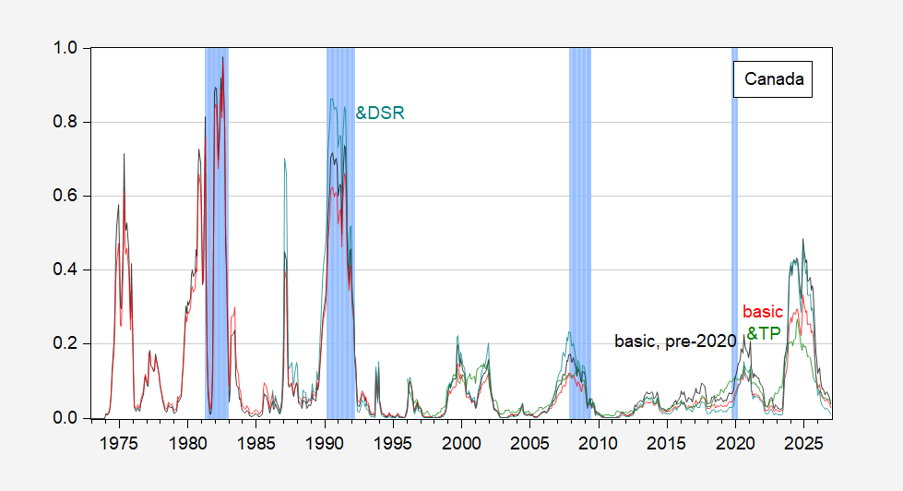
Figure 6 from Chinn and Ferrara (2026): the probability of a Canadian recession. Light blue indicates ECRI-defined peak-to-trough recession dates. Note: Recession probability estimates correspond to predicted dates, not forecast dates. Assume no recession until April 2026.
On the other hand, the spread term has never been positive and is followed by a recession (at least since 1970). Therefore, the indicator-based evidence for a recession starting is weak (and weak, based on historical correlations, for a recession in 2026). Of course, the previous 12-month indicator cannot account for “surprises” like the drastic escalation of the trade war.