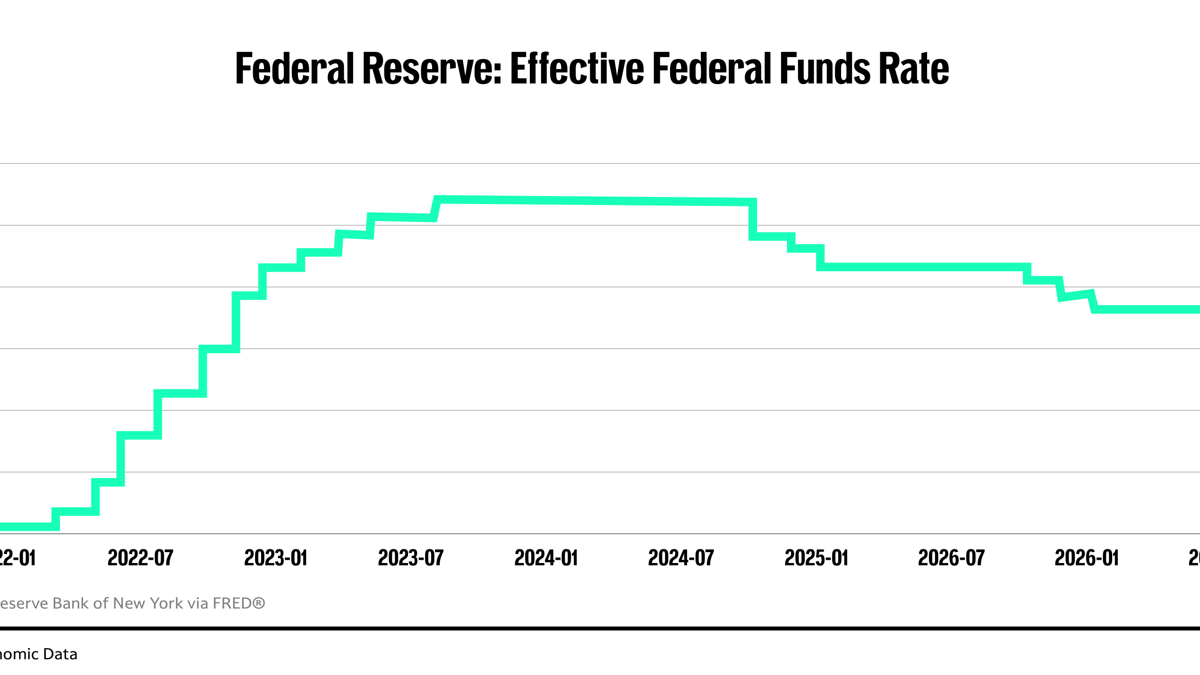
The U.S. economic community reacted to the hot September CPI data released on October 14 with a range of reactions, from soaring 10-year Treasury yields to traders surging the probability of a rate hike at the Fed’s October 27-28 meeting to 32.7%, to new questions surrounding the sustainable run rate of artificial intelligence models.
I honestly don’t know why everyone is so surprised. I’m more of a Main Street person than Wall Street, and I know that the 3.7% year-over-year CPI headline number will be higher than the consensus of 3.6%.
That’s because every time I pay a bill or make a purchase, the price is always higher than expected. I’m checking gas prices in my town. Also, I finally turned on the heat (very low) because life in New England is getting chilly and the temperatures outside are only going to continue to drop.
Now, I know I have no power over the Fed’s monetary policy decisions. I’m simply describing what the Fed is doing and what its respected economists and policymakers are saying.
For example, the Fed’s Beige Book, released on October 14, was generally a bit “boring,” except for this ominous quote: “Businesses in several regions cited ongoing uncertainty around energy and tariffs and expected further price increases in the coming months.”
Inflation adds to huge price pressures across the economy
Now, over the past year, between energy surges, tariffs, the Iran war, and the hyperscale demand for artificial intelligence, everything in my life has become more expensive, whether it’s writing an insurance check, filling up my Honda Fit with gas, or filling my closet with new clothes because I lost 60 pounds on GLP-1 pills. (BTW, this is another huge expense – nothing actually fits. My jeans are sagging dangerously low. Even my shoes are flapping.)
So with my dwindling savings, new stingy skills, and a significantly smaller monthly budget, I’m leaning toward the lower end of the K-shaped economy.
More from the Fed:
- JPMorgan expects Fed to raise interest rates sharply this year
- The Fed’s October interest rate hike depends on two upcoming economic reports
Perfect example: Late last week, I was staring at an empty refrigerator two days before hosting a birthday brunch for my beloved family. The kitchen shelves are equally sad. Frankly, so does my wallet.
I scribbled down the ingredients for a casually elegant brunch menu, checked out the Whole Foods app, and quickly realized it cost as much as the GDP of a small country. I then checked on the app for the same ingredients at my beloved local supermarket Hannaford, a subsidiary of Netherlands-based multinational retail holding company Ahold Delhaize.
These prices are still pretty rough. But I grabbed my car keys and grumbled as I walked into the store’s parking lot until I realized there was an Aldi across the street from Hannaford.
As we say in New England, I made a U-turn and made my food retail debut at an unpretentious German discount supermarket that industry experts say is effectively cannibalizing the lunches of other supermarket industry leaders.
I filled my shopping cart with everything on my list, opened the register, and started pulling four $20 bills out of my wallet. Total: $35.69.
I was just dumbfounded. In the other two stores I studied, the ratio was less than half. (Based on the rave reviews, the brunch is absolutely delicious.)
Inflation creeps into Election Day
Monetary policy has two congressional mandates: employment maximization and price stability.
Fiscal policy is a hotly debated topic that is likely to lead to political rhetoric or fat-splitting spending.
So whether the Fed raises the benchmark federal funds rate by 25 basis points to boost short-term interest rates on October 27-28, December 8-9, or both, such rate increases will have little direct impact on my daily life.
The October meeting poses significant political and economic timing issues, as raising rates six days before Election Day could bring additional scrutiny to the Fed’s independence.
The December meeting will provide a new perspective on employment, inflation and economic growth.
RELATED: Fed’s Waller takes ‘U-turn’ on interest rate outlook as inflation surges
But if, over the long term, a rate hike or interest rate hikes can alleviate price pressures on millions of American households, consumers and families, it will be worth it.
Within days of the October Federal Open Market Committee meeting, many of these Americans will be voting in the divisive midterm elections on November 3.
On the ballot will be important local issues: roads, schools, fire, police and other community priorities from the state Capitol to our own homes.
There will also be 435 congressional seats and 35 U.S. Senate seats on the ballot.
Americans will vote with their inflation-plagued wallets in 2026
My Spider-Man Sense: Many of my American voters don’t think about bull markets, Mag 7, or corporate profits when they vote.
They think about their wallets and the inverse relationship between high inflation and quality of life.
They don’t need to know that CPI increased by 3.7% year-on-year in September, nor do they need to know that gasoline prices increased by 9.1% from the previous quarter and 34.2% from the same period last year.
They know they have a sinister feeling inside them that will taint their bank accounts and shrink their retirement portfolios.
That’s how they vote.
Oh, and if you come to me after I vote in the high school gym, I head to Aldi after deleting the Whole Foods app from my phone.
Goodbye, Felicia.
Related: JPMorgan expects Fed to raise interest rates sharply this year